Property claims
Home, Business and Fire Insurance Claims
Water, fire, contents, repair disputes and the contractual scope of cover.
Read the Turkish guide →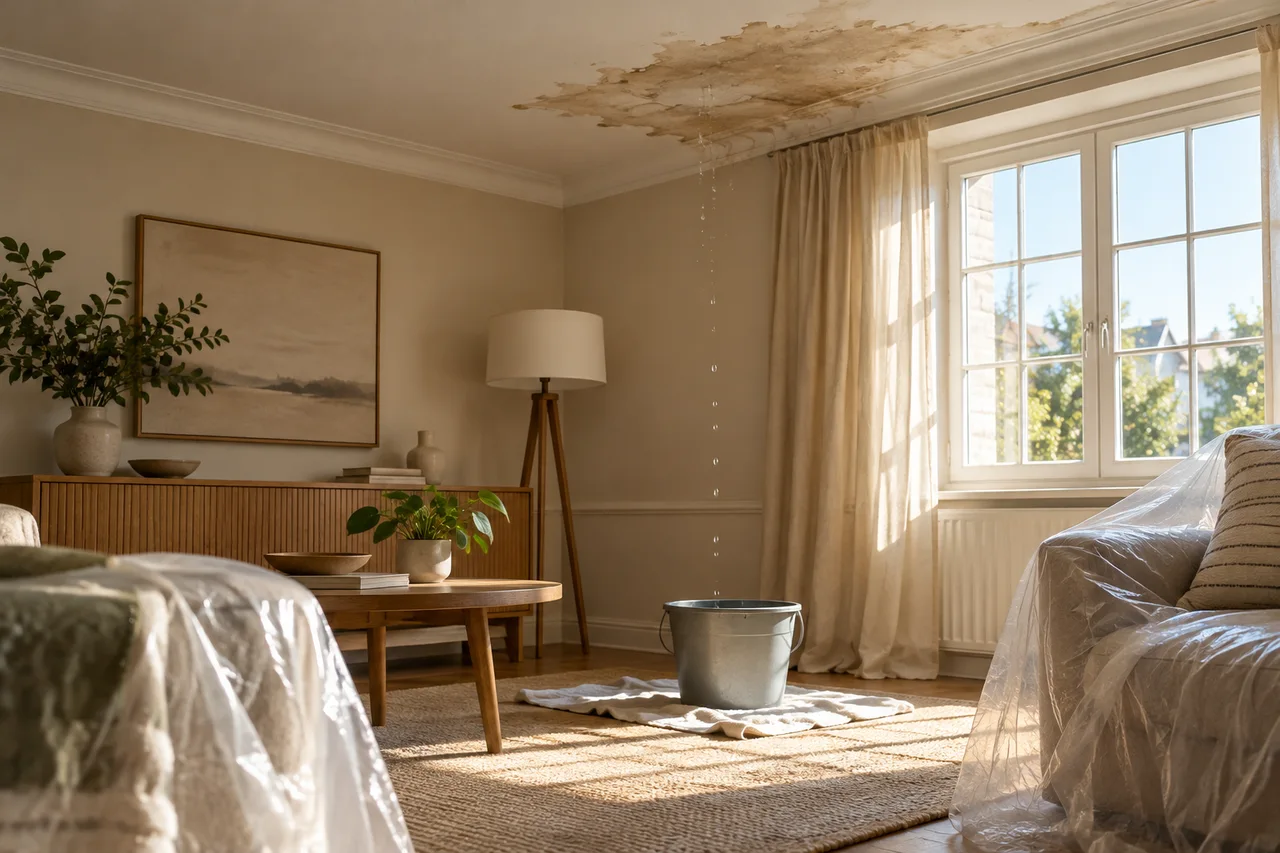
01 / LEGAL PREPARATION
Use the policy as a map of the actual insured risks
A property product name is not a complete explanation of cover. Read the schedule, insured interests, listed risks, extensions, limits, deductibles and special conditions together. Identify the building, contents, business property or liability interest relevant to the request. Fire damage, a water incident and a claim for interrupted business may involve different provisions and evidence. Keep the policy version that applied when the event occurred, including any endorsements. An application should show which provision and factual event support each requested item. This makes it possible to distinguish a coverage disagreement from a disagreement about the repair cost. It also avoids assuming that every expense associated with a damaged home or business automatically falls within the same insurance contract.
02 / LEGAL PREPARATION
Document the cause as well as the visible damage
Photographs show the condition of the property, but the cause and sequence of the incident may need additional records. Keep available fire, emergency, maintenance, plumbing or technical reports and relevant communications. For a water incident, for example, distinguish the source, affected areas and subsequent measures from earlier defects or unrelated repairs. Where a landlord, tenant, building management or contractor is involved, identify their roles and documents separately. The policy assessment and a potential responsibility claim against another person are different enquiries. A technical finding about the cause should be read in full rather than inferred from the appearance of one damaged room. The purpose of the evidence file is to explain what happened, what it damaged and why the requested work is linked to that event.
03 / LEGAL PREPARATION
Compare repair estimates and completed work
Organise estimates, authorisations, invoices, payment evidence and expert recommendations by item. State which work restores the insured damage and which work concerns other improvement or maintenance. If there is a disagreement about quantities, materials or labour, identify it alongside the relevant report. A higher total estimate may include different work rather than a higher cost for the same repair. When repairs have already been completed, keep dated photographs and the documentation available before the work began. The insurer may need to understand the original condition as well as the final invoice. The legal review can then distinguish the evidence of actual damage from disagreements about the authorised scope, valuation, deductible or a proposed contractual exclusion.
04 / LEGAL PREPARATION
Contents and business interruption need their own records
Where a claim concerns furniture, equipment, stock or other contents, identify the items, ownership and available value evidence. A photograph of a room does not by itself establish the full purchase history or present value of everything claimed. For a business interruption request, establish whether the policy provides the relevant cover and what conditions apply. Then connect the interrupted activity, period and financial effect to the event. Gross sales, profit and additional expenditure are different figures. Accounting records, contracts, activity history and mitigation arrangements may be useful to explain the actual request. Do not add a broad estimate of lost business to a building repair claim without identifying its contractual basis and supporting evidence. Each category should be assessed on its own documents.
05 / LEGAL PREPARATION
A focused response to a property claim refusal
Read the insurer’s refusal with the policy, expert material and documents submitted. Identify whether it disputes the insured risk, cause, policy information, valuation or evidence of a particular item. Address that ground directly. Keep separate communications concerning another responsible party, because those do not automatically resolve the insurance request. If a payment has been made, record the items it was said to cover and compare them with any remaining request. A proposed settlement should explain its scope and treatment of related claims. Whether an insurer application, arbitration or court proceeding is suitable depends on the case and parties. The office can review that route after the factual and contractual questions have been made clear, without treating every property loss as the same type of dispute.
PRIMARY REFERENCES