Motor claims
Vehicle Loss of Value Claims in Türkiye
Evidence, previous damage, underpayment and a later vehicle sale.
Read the guideINSURANCE LAW IN TÜRKİYE
Insurance Lawyer · Av. Murat Adar
From vehicle damage and personal injury to property cover and arbitration: understand the decision, organise the evidence and identify the next legal step.
THE ENGLISH KNOWLEDGE CENTRE
Choose the closest subject. Each guide explains the evidence, disputed questions and practical preparation for a legal review.
Motor claims
Evidence, previous damage, underpayment and a later vehicle sale.
Read the guideMotor claims
Rejected vehicle damage claims, repair disputes, total loss and salvage.
Read the guideProcedure and evidence
Insurer applications, documents, costs, procedural stages and decisions.
Read the guideInjury and liability
Medical evidence, income loss, temporary incapacity and lasting effects.
Read the guideInjury and liability
Review payment demands, insurance recovery lawsuits and supporting evidence.
Read the guidePolicy disputes
Treatment authorisation, pre-existing conditions, renewal and group policies.
Read the guideMotor claims
Compare the market valuation, damaged-vehicle treatment and the actual net offer.
Read the guideMotor claims
Repair periods, replacement transport and documented interruption of vehicle use.
Read the guideInternational matters
Identify the accident location, vehicle registration, insurance and bureau route.
Read the guideInjury and liability
Uninsured or unidentified vehicles, eligible losses and the evidence of the incident.
Read the guidePolicy disputes
Beneficiary documents, credit-linked cover and the basis of an insurer refusal.
Read the guideProperty claims
Policy details, building damage, inspection reports and separate private insurance.
Read the guideProperty claims
Water, fire, contents, repair disputes and the contractual scope of cover.
Read the guideInjury and liability
Read compulsory traffic and additional liability layers as separate cover arrangements.
Read the guideInjury and liability
Support relationships, income evidence, beneficiaries and separate loss categories.
Read the guidePolicy disputes
Schedules, endorsements, exclusions, obligations and the questions a claim file should answer.
Read the guideA CLEAR FIRST DISCUSSION
A complete folder is useful when it explains the disputed decision. Put the narrative, evidence and requested remedy in a clear order.
Identify the incident, relevant parties and policy period.
Keep the insurer’s answer, offer or recovery demand.
Connect each requested loss with its supporting records.
Assess the application, arbitration or court requirements.
BEFORE YOU APPLY
Explore the questions that connect the contract, incident, loss and procedural stage.
01 / PREPARATION
Begin with the event and the disputed decision, rather than with the name of a court or a promise of compensation. A road accident can produce repair cost, market loss, bodily injury and other questions, but those items do not necessarily share the same insurer, evidence or legal route. A health policy rejection has a different starting point from a demand by an insurer to recover money from you. Identify the claimant, insured person, policyholder, vehicle owner and other relevant parties. A person can occupy more than one of these roles, but they should not be assumed to be identical.
Make a short case map showing each requested remedy, its proposed recipient and its supporting documents. Record whether there has already been an insurer application, payment, formal demand, arbitration or court proceeding. This map makes the first discussion more useful: it allows the office to identify missing material and relevant procedural questions before spending time on a detailed calculation or a lengthy account of the event.
02 / PREPARATION
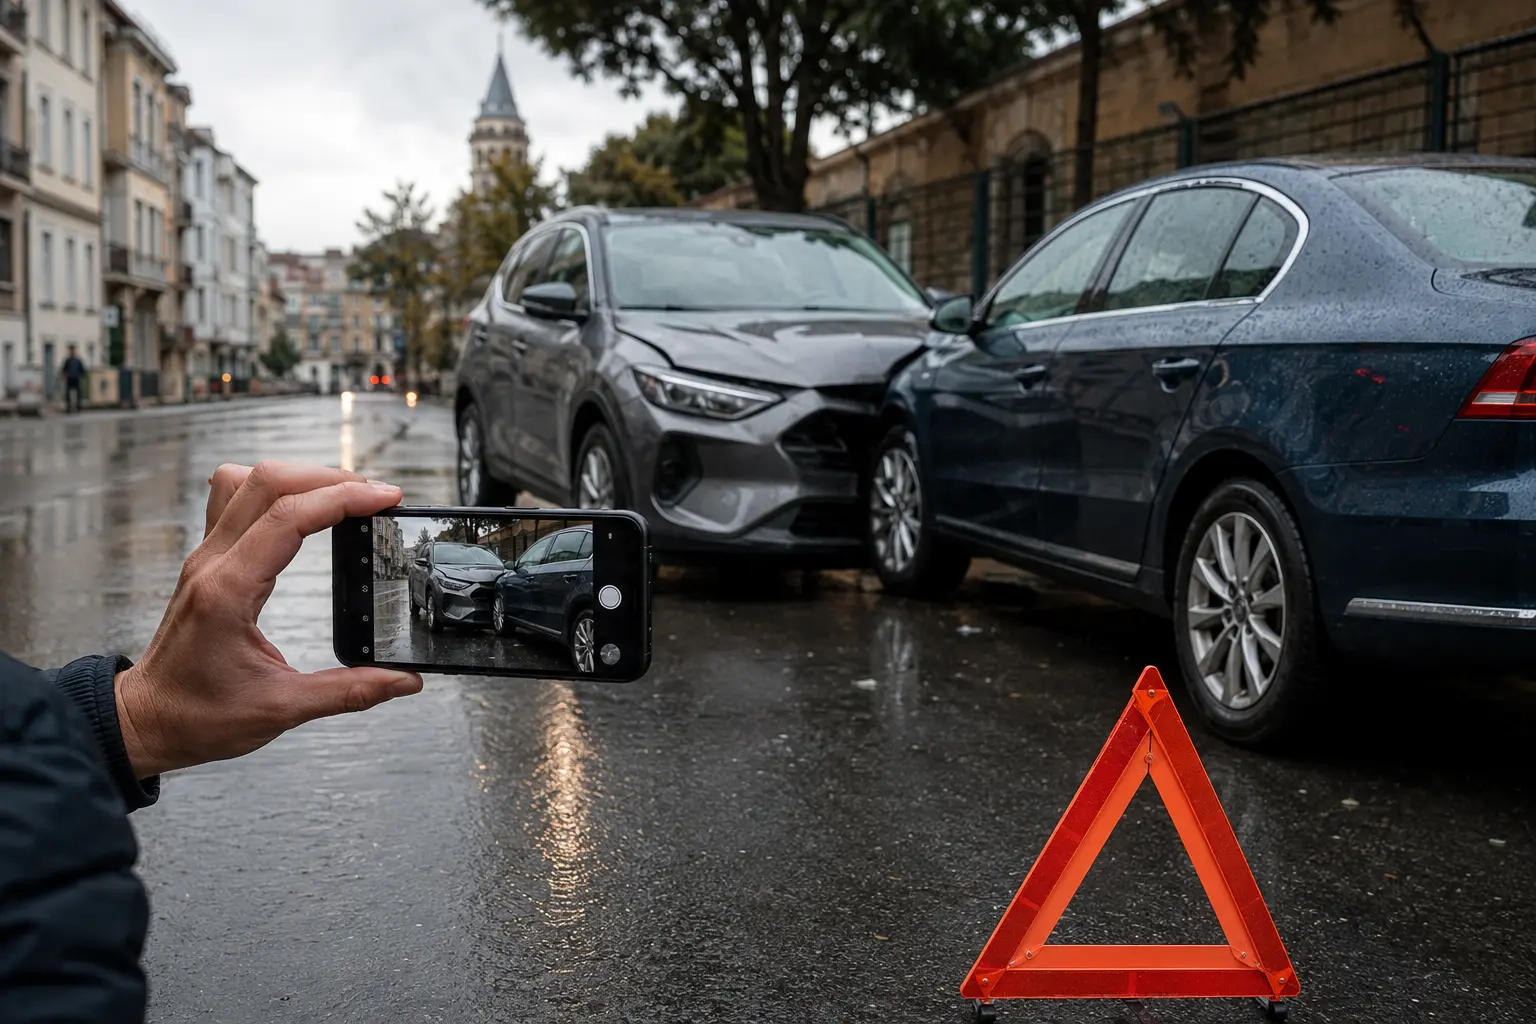
A repair bill describes work on the vehicle. A loss-of-value assessment concerns the effect on its market position after repair. A total-loss offer may involve market valuation, salvage and transfer of ownership. These issues should be recorded separately. Collect the accident material, photographs, registration, mileage, expert report, repair breakdown, insurer application and payment correspondence. If there is earlier damage, compare affected parts and repair dates instead of relying on one total claim-history figure.
For a low offer, identify which input needs review. Is the disagreement about fault, comparable market values, previous damage, authorised repair work or a deduction? Explain that issue with the relevant material. A later vehicle sale or a payment described as a settlement may introduce a question about who can still pursue a request or what the payment covered. Keep the complete sale, release or assignment document with the claim file. The detailed English vehicle guides explain how to prepare those comparisons without treating an online estimate as an assured recovery.
03 / PREPARATION
For an injury case, record the accident, hospital attendance, treatment, follow-up and periods away from work in date order. Medical evidence and the official incident material serve different roles. A diagnosis establishes a health fact; the connection with the incident and the effect on the claimed loss may still require examination. A treatment-related absence and a lasting effect on working capacity are separate questions. They should not be collapsed into a single percentage or one compensation figure.
Employees may need payroll, employment and absence records. Independent workers may need activity, tax, invoice and other evidence explaining the actual income impact. Keep records of previous insurer or social-security payments so that overlap can be considered. Medical or care expenses should be associated with itemised records rather than included without explanation in a total demand. If the accident occurred during work or employer-arranged transport, employment and social-security issues may also need a separate case map. The office reviews the legal requests and evidence; medical findings require appropriate medical assessment.
04 / PREPARATION
Request the insurer’s written reason and read it with the policy and the documents submitted. A claim left pending for more information, a complete rejection and a partial payment are different situations. A response should identify which one applies. If the insurer disputes coverage, match the cited contractual provision to the alleged facts. If it disputes the amount, obtain the relevant calculation or report and show the particular input or deduction that needs review.
Create a record of applications and answers with the dates, attachments and evidence of delivery. When there is a payment, identify the loss item and settlement document it concerns. Credit amounts already received when explaining any remaining request. A vague statement that insurance did not pay enough is less useful than a clear comparison of the request, report, payment and outstanding issue. The appropriate reconsideration, arbitration or litigation route can then be evaluated against the actual dispute. The same approach helps distinguish the insurer’s position from a separate workshop invoice or third-party demand.
05 / PREPARATION
Insurance arbitration is a particular procedure with eligibility and prior-application requirements. It should not be selected only because someone describes it as quicker. Identify the insurance branch, insurer, claimant’s interest, disputed request and prior application. Check whether the same dispute is already before another relevant forum. Company participation, compulsory-insurance rules and current procedural requirements must be assessed for the particular case. The detailed arbitration guide links to official Commission information and the corresponding Turkish guide.
A court claim may involve different defendants, prerequisites and questions of jurisdiction. A claim against a driver, vehicle operator or another responsible party is not automatically resolved in the same proceeding as a claim against the insurer. Once the route is identified, organise the requested relief and attachment list for that procedure. Keep the decision timetable separate from the timetable for actual recovery. Expert work, notification, possible objections and implementation can each introduce a further stage. A procedural explanation should show those stages instead of promising a fixed date on which every client will receive money.
06 / PREPARATION
For a foreign-plated vehicle, record the accident location, registration country, vehicle and driver details, insurance documents and any Green Card material. The responsible insurer or bureau must be identified from the actual coverage relationship. Keep the official incident and damage records together, including documents issued in another language. Do not assume that the country of residence alone determines which law, insurer or procedure applies.
For a client living abroad, the first review can establish what is already available electronically and what may need an original, translation or formal authority document. Representation and document requirements depend on the intended procedure. The office can explain the relevant preparation after the parties and route are identified. Sending a large folder without an incident summary or a list of missing documents may make the review slower. A concise chronology, policy and insurer answer usually create a more useful starting point than a speculative compensation calculation. The scope and communication arrangements should be agreed for the actual matter.
07 / PREPARATION
If an insurer or lawyer asks you to reimburse a payment, identify the underlying incident, recipient, paid loss items and stated recovery ground. Then distinguish an ordinary demand letter from an enforcement payment order or a court-served claim. The formal document and notification record determine the procedural assessment. The merits review separately addresses the alleged responsibility, policy provisions, payment evidence and amount. The English recourse guide explains how to arrange these materials without assuming that every demand uses the same legal basis.
For health insurance, place the hospital request beside the insurer’s written decision. Compare the treatment, policy period, special conditions and stated reason. Existing-condition allegations, treatment reimbursement, authorisation, renewal changes and group-policy transitions are different issues. A medical chronology is relevant to some of them, while a contractual comparison is essential to others. Keep the health declaration, offers, guarantees and insurer correspondence where relevant. A clear request identifies the specific decision to be reviewed and the remedy sought, rather than treating all problems under a health policy as one generic rejection.
08 / PREPARATION
The proposed work should identify whether it covers a document review, insurer application, arbitration, litigation, expert-report objections, decision review or implementation. These are not automatically included in every instruction. Ask for the agreed scope and fee arrangements in writing. A lawyer fee is different from the Commission’s application fee, notification expense, expert cost or other procedural expenditure. Current official tariffs should be checked for the relevant transaction and claim amount.
A possible costs award is not money already received and should not be presented as automatic reimbursement of every expense. The agreement should explain how payments, procedural expenses and any further stage are handled. A quotation is easier to evaluate when it describes the work and exclusions clearly. The office does not publish one guaranteed price for every insurance dispute because the documents, parties, value and required stages differ. The initial review can define the work that is actually needed, allowing the client to understand the proposed representation before deciding how to proceed.
09 / PREPARATION
Prepare a one-page chronology identifying the event, policy, application, answer and any payment or notification. Add a document index rather than repeating the same account in several messages. Clearly mark missing documents and points you do not know. For vehicle matters, the principal report and repair breakdown are useful; for an injury matter, the medical and income chronology matters; for a recovery demand, the complete demand and formal procedural documents are central. The relevant guide provides a more detailed topic-specific preparation method.
The first discussion should establish the disputed decision, available evidence, current stage and possible next step. It should also identify whether a technical or medical assessment is needed separately from legal review. A document-led approach does not promise a result, but it allows the reasoning behind a proposed application or defence to be explained. Once the route and scope are agreed, the work can be organised into applications, evidence, responses and follow-up. Contact Av. Murat Adar through the office details below and state the subject and present stage of your matter.
10 / PREPARATION
An insurance offer is more than a number. For a damaged vehicle, it may include a proposed ownership transfer, treatment of salvage, deductions or a release. For another policy, it may identify particular expenses but leave other items unresolved. Read the complete written proposal and associate each amount with the underlying assessment. A headline market value, an expert’s repair estimate and a net settlement amount are different figures. They should not be compared as if they represented the same obligation.
Use a table containing the requested item, evidence, insurer assessment, payment and disputed balance. Add any action expected from the client, such as signing a document or transferring property. Identify who is responsible for completing that action and how it relates to payment. The purpose is to make the practical and legal effects visible before accepting an arrangement. The new total-loss and salvage guide explains this approach for vehicle offers; the policy review guide explains how to connect a proposed agreement with the contractual documents. Neither a calculation nor a proposal should be treated as a completed recovery before the relevant obligations are understood.
11 / PREPARATION
A damaged property can produce several different requests. The building repair, damaged contents, temporary arrangements and interruption of a business should be listed separately. Identify which policy or other legal relationship is relied on for each item. Compulsory earthquake cover and a private property contract may have different roles, and a landlord, tenant or building management dispute may create an additional question. A single invoice or photograph rarely answers all of those enquiries.
An initial file should contain the relevant policy, property identifiers, available cause and damage reports, dated photographs, work estimates and insurer correspondence. Where work has begun, keep the material showing the condition before repair alongside the completed-work records. If another person is said to be responsible, retain their communications separately from the insurer’s decision. The new property and DASK guides explain how to compare the event, covered interest, expert material and payment. A claim should be built around documented damage and the actual contractual scope instead of assuming that every expense incurred after a property incident has the same recipient or recovery route.
12 / PREPARATION
An insurance matter following a death may concern a life policy benefit, a credit-linked arrangement, a loss-of-support request after an accident or several separate issues. The persons entitled to make those requests may need to be identified under different documents and rules. An inheritance record, policy beneficiary designation and evidence of financial support should not automatically be treated as interchangeable. State who makes each request, what is sought and which contract or event supports it.
Keep policy and loan material, relevant event records, beneficiary documents, evidence of income or support, insurer answers and payment records in separate indexed groups. If more than one person has made an application, retain the full correspondence and explain its scope. Any release or settlement should identify whose request it addresses and what it resolves. The life insurance and fatal accident guides offer different preparation methods for these different files. This helps the initial discussion focus on actual capacity and evidence, rather than turning a family’s several financial questions into one universal compensation figure or assuming that one institutional payment closes every possible request.
13 / PREPARATION
An unidentified vehicle, an uninsured vehicle, a foreign plate and a claim exceeding one policy’s scope are distinct situations. Record the facts and documents establishing the particular situation before deciding which institution or insurer to approach. A Green Card or bureau enquiry does not replace the investigation of the accident and loss. Similarly, the existence of the Guarantee Fund or an additional voluntary liability policy does not establish automatic cover for every item requested.
Create a recipient map showing each loss category, possible party or institution, relevant document and outstanding enquiry. Update it when an insurer, policy or vehicle is identified. Keep payments associated with their stated loss items and record another proceeding if one exists. The new foreign-plated vehicle, Guarantee Fund and İMM guides describe these different preparation questions. They are intended to help organise a real file for legal review. They do not present the institutional route as a shortcut around the evidence of responsibility, claimant status, actual loss or the conditions of the relevant policy and procedure.
14 / PREPARATION
A client may say that a claim is delayed when the vehicle is still being repaired, the insurer has not issued a final answer or an agreed payment has not arrived. Those are different stages. Identify the last documented event and the action still expected. Keep the workshop dates, insurer document requests, report dates, written decision and any payment proposal in one chronology, but distinguish the organisations responsible for each part of the process.
Where loss of vehicle use is claimed, the repair chronology and actual effect on use require their own evidence. Where the insurer’s procedure is disputed, establish what it received and what it answered. Where a decision or agreement already exists, compare its terms with what has been implemented. A general statement that the entire case has taken too long does not identify the appropriate next demand. The new unavailability guide addresses repair and interruption evidence, while the arbitration and contract guides address different procedural and contractual questions. This division allows the office to explain what the proposed next step is intended to resolve.
15 / PREPARATION
After the principal documents have been reviewed, a useful plan identifies the current dispute, missing material, suitable next application and any separate technical assessment. It should explain the proposed work and who will provide each part of the evidence. A legal review, an expert valuation and a medical assessment do not have the same function. The plan can also distinguish a first insurer request from an existing arbitration, court or implementation stage.
Clients should be able to understand the agreed representation scope, lawyer fee and anticipated procedural expense categories. If a later stage is outside the initial instruction, that should be clear when the work is discussed. The office’s English guides are organised around these practical questions so that visitors can arrive with a focused summary rather than a prediction of a guaranteed result. Start with the guide closest to your matter, note the missing documents and current stage, then contact Av. Murat Adar through the details at the end of the page. The discussion can then address the particular contract, incident, evidence and route that actually require attention.
PRIMARY REFERENCES