01 · SCOPE OF SUPPORT
What does this procedure involve?
Even where there is no disagreement within the family, recording an inheritance with the relevant institutions takes time and document follow-up. Uncertainty about the correct sequence can mean applying repeatedly to the same institution or having a document corrected.
The starting point is to identify the heirs, known assets and any information about debts or ongoing cases. Where debts may exist, the legal position on acceptance and rejection of the inheritance should be considered before beginning routine transfer procedures.
Establishing the file
An initial procedure map is prepared using the death record, family relationships, any existing certificate of inheritance and the known assets.
Registration of inherited property
Documents and applications for registering property in the heirs’ names are followed up, with an explanation of the effects of the applicable form of co-ownership.
Bank and institutional applications
The documents requested by each institution are collected, and the procedure for accounts or other rights is determined for the particular file.
Heirs living abroad
Legalisation, translation and power of attorney requirements are identified, creating a timetable that fits the procedures in Turkey.
02 · THE PROCEDURE
From preparation to follow-up, step by step
Identify the heirs and existing documents
Death and civil registry information, any certificate of inheritance, differences in family records and known debts are considered.
Classify the assets
Separate authority and document lists are prepared for property, accounts, vehicles and other rights.
Sequence declarations and applications
The stage at which each document is needed is identified, keeping tax duties and other institutional obligations distinct.
Follow up inheritance transfers
Applications are made within the power of attorney, requests for missing items are addressed and completion documents are obtained.
Consider distribution separately
If the heirs want particular assets allocated to particular people, any later distribution or sale is planned separately from registration of the inheritance.
03 · DOCUMENT PREPARATION
Documents and preparation checklist
0 / 6 document categories prepared
Use this as a preparation checklist. The authority or your circumstances may require additional documents. Selections are cleared when you leave the page.
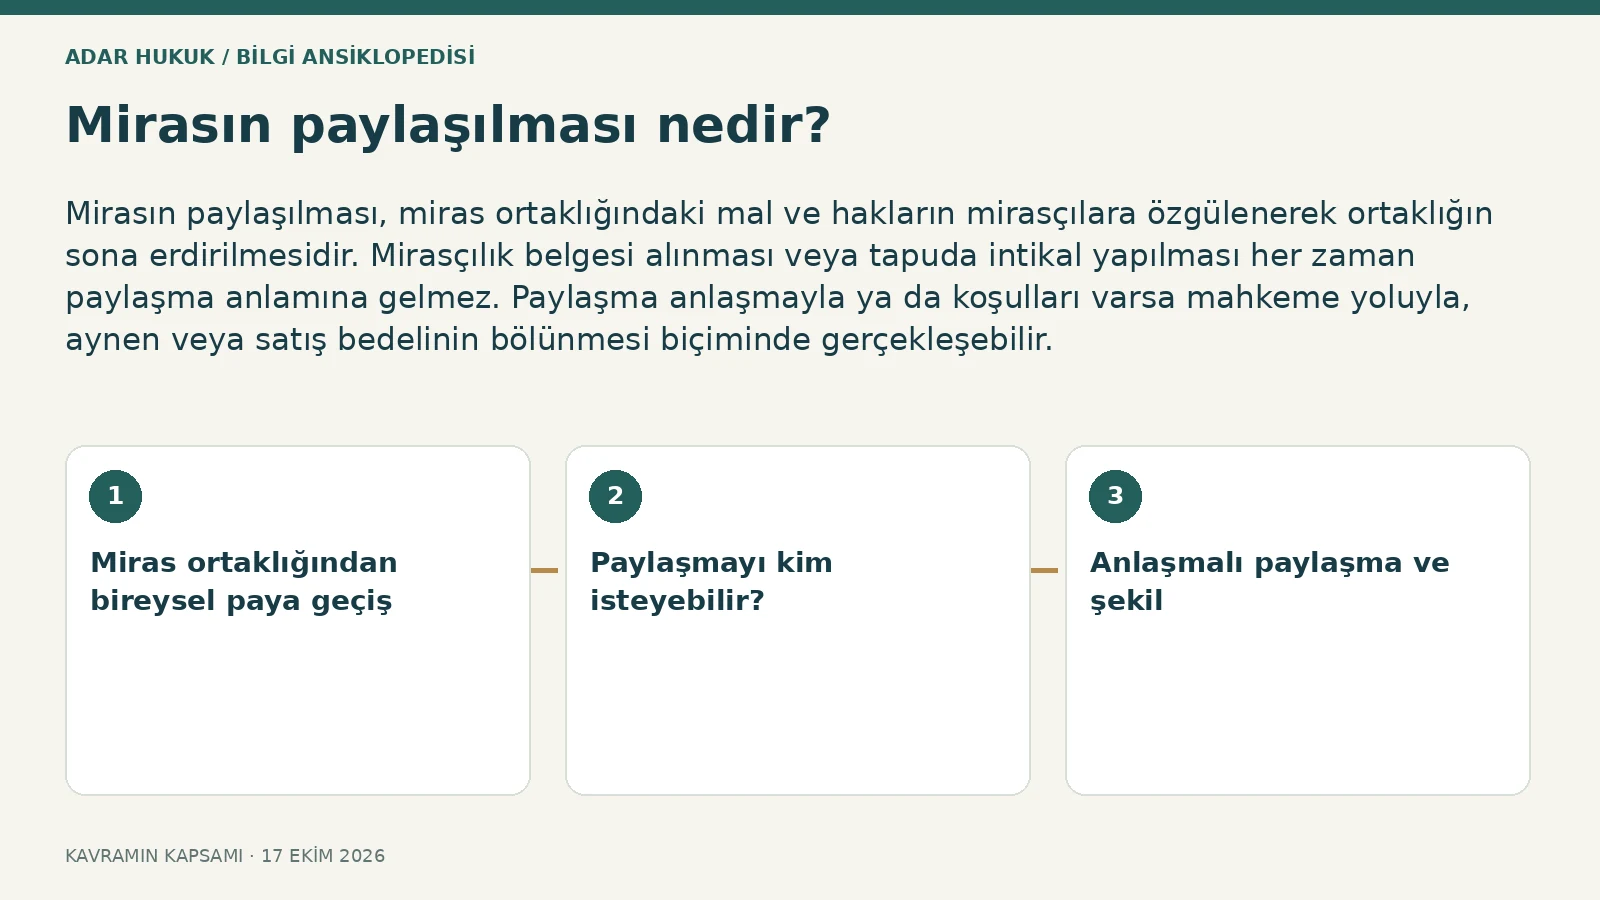
Registration and distribution are different steps
An inheritance transfer records inherited rights in the relevant registers. Applying for registration does not, by itself, make each heir the sole owner of a particular home or account.
Distribution among the heirs requires separate consideration. Selling one person’s share, selling assets jointly or allocating particular assets to particular heirs may require different documents and procedures.
Tax obligations require separate follow-up
A certificate of inheritance does not replace a tax declaration. The place of death, the circumstances of the heirs and information about the assets are considered when establishing filing dates and document requirements.
Tax calculation, payment and any required tax clearance procedures are treated as separate steps. If the file requires accounting or specialist tax services, that work is planned with the relevant professional and the costs are explained in advance.
Files involving several countries or incomplete records
The usual sequence may change if the deceased or an heir is a foreign national, documents were issued abroad or family records contain discrepancies. A foreign document is not automatically assumed to be usable in Turkey.
Where civil registry details are missing, names differ or certificates of inheritance conflict, their effect is investigated first. If institutional follow-up cannot resolve the issue, any need for court proceedings is explained separately.
POINTS TO WATCH
Common mistakes and important distinctions
Acting before considering debts
Steps taken before the legal consequences of inheritance are examined may affect the options available later.
Assuming registration completes distribution
It is necessary to establish whether co-ownership continues and which heir has rights over which assets.
Using one institution’s checklist for every procedure
Banks, land registries and tax offices may have different document requirements.
PLANNING THE WORK
Legal fees, expenses and timing
How are fees and expenses determined?
Fees are determined by the variety of assets, the institutions involved, the number of properties and the legal work required, rather than by the number of heirs alone. A title deed transfer on its own has a different scope from combined land registry, bank, tax and foreign-document follow-up. Notarial fees, court fees, translation, legalisation, institutional charges and taxes are separate expenses. Existing documents are considered at the first consultation, and the included procedures are explained in writing. If a distribution dispute, correction of the certificate of inheritance or another court matter becomes necessary later, the scope and fee for that additional work are agreed separately.
What can affect the timetable?
Timing depends on whether the certificate of inheritance is already available, the consistency of the records, the institutions holding the assets and the heirs’ representation arrangements. Registering one property does not follow the same timetable as handling assets in several cities and accounts at different banks. Obtaining foreign documents or correcting family records may add stages. The priority is to identify time-sensitive obligations and make the necessary applications on time. Estimates are shared by stage after the initial document review. A fixed completion date is not given for procedures that depend on an institution’s response.
HYPOTHETICAL EXAMPLE
Illustrative situation: inheritance procedures for two siblings living abroad
This is a hypothetical situation explaining the process. Two siblings live abroad and want to complete the procedures for an apartment and bank account inherited from their father. They have obtained a certificate of inheritance, but the apartment is still registered in their father’s name. The first step is to gather the heirs’ details in the certificate, the property record, known bank information and any debt information. It is clarified whether the siblings want registration alone or a later sale and distribution as well. Powers of attorney are prepared with the appropriate scope. Separate lists are created for the land registry, bank and tax procedures. Completion documents are sent to the siblings as institutional requirements are fulfilled. If they want the apartment allocated to one sibling, the separate distribution or transfer step is explained and a new procedure plan is prepared.
QUESTIONS AND ANSWERS
Frequently asked questions
Do all the heirs need to travel to Turkey?
Many institutional procedures can be handled by a representative with appropriate authority documents. The type of transaction and the heirs’ particular circumstances are considered separately.
Can one heir apply for registration of inherited property?
An application by one heir may be possible for registration under joint ownership without individually disposable shares (elbirliği mülkiyeti). Conversion to ownership in defined shares and distribution are subject to different requirements.
I have the certificate of inheritance. Are there further steps?
Land registry, bank and tax procedures may remain, depending on the estate. The certificate does not mean that every record has been updated automatically.
I think the estate may have debts. What should I do?
Mention the possible debts and any dates you know when first contacting us. Legal options should be assessed before proceeding with inheritance transfers.
Is this service sufficient if the heirs disagree?
Administrative follow-up and inheritance or distribution disputes are different services. Any additional route and the required representation are explained after review.
READ THE ORIGINAL SOURCES
Official sources and application information
- TKGM — Guide to land registry transactions ↗
Framework for inheritance registration, representation and documents.
- Revenue Administration (GİB) — Tax obligations of heirs ↗
Declarations, tax obligations and access to current official guides.
This English edition was prepared on 10 November 2026 from the Turkish guide dated 9 November 2026, retaining its official sources. Editorial dates are not legislation commencement dates or a record of individual lawyer approval. Some sources are in Turkish. Current authority requirements and the circumstances of your matter must be considered together. Editorial policy (Turkish)